 plan
A three-year wait to sell a one-bedder: unpacking Singapore’s resale gap
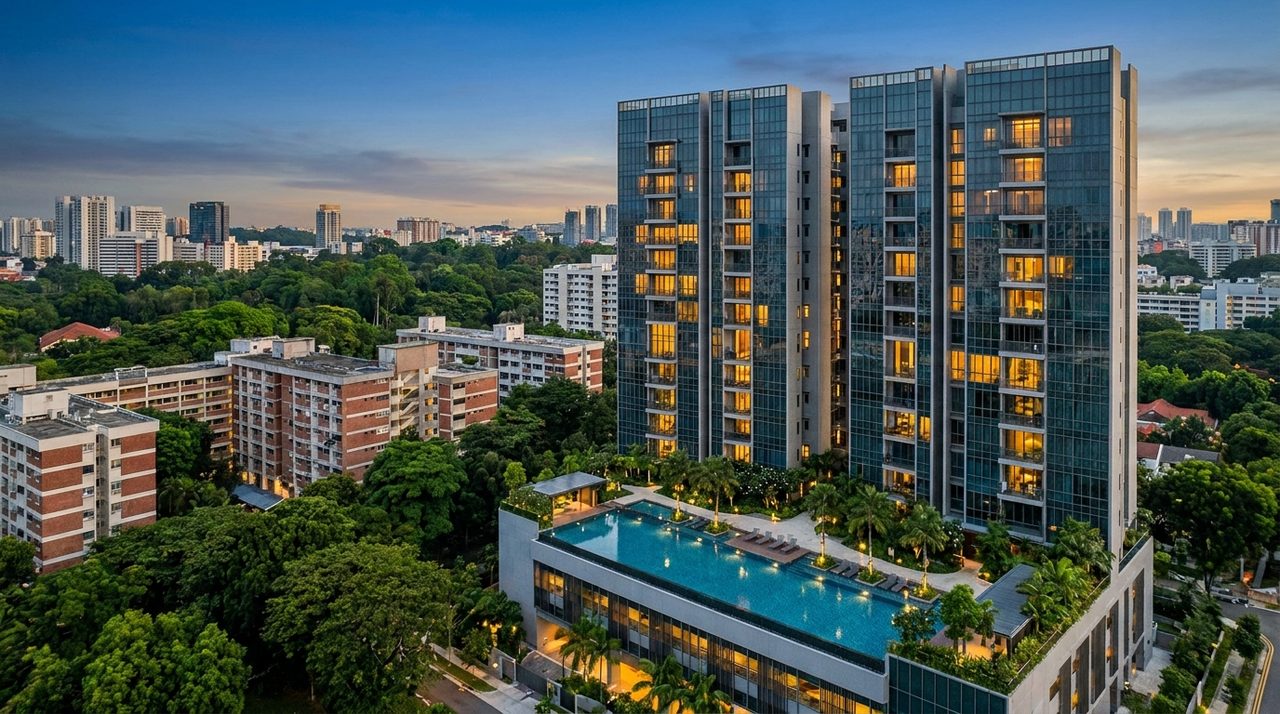
A Marina Bay Residences owner’s slow exit puts a human face on a 2025 study showing weaker resale gains for studios and one-bedroom units.
An investor waited three years to sell her one-bedroom apartment at Marina Bay Residences, eventually accepting $1.6 million in August 2025. She had bought the 732 sq ft home for $1.55 million in 2016. The seller, described in a September 2025 report as a 51-year-old French national living in Singapore, was not publicly named.
Her sale left a difference of just $50,000 between purchase and sale prices, before costs or rental income. Alongside her experience, the report detailed an ERA Research and Market Intelligence study in which studios and one-bedders recorded slower price growth than larger apartments. For someone considering a compact condo, the interesting question is not simply whether it will attract a tenant, but how readily another buyer will eventually take it over.
What did the study actually find?
The September 8, 2025 report described an ERA analysis covering 146 non-landed residential projects and 24,327 resale transactions. Studios and one-bedroom units accounted for roughly one-quarter of the sample’s resale transactions from 2019 to 2025—a meaningful share of activity, rather than an absent market.
The difference lay in performance. From 2019 to 2024, studios and one-bedders recorded average annual price growth of about 3%, compared with 5% to 8% for two- to five-bedroom units, according to the reported study.
The profitable-resale figures also favoured larger homes. Some 89% of studios and one-bedders resold at a profit, compared with 93% of two-bedders, 95% of three- and four-bedders, and 99% of five-bedders.
Put another way, for every 100 studio and one-bedroom resales in that comparison, about 11 fell outside the profitable category, against seven for two-bedders. That is a useful difference, but it also leaves an important fact intact: most of the smallest units in the sample resold above their purchase prices. These counts are an illustration calculated from the study’s reported percentages.
The underlying ERA study is not available here as a standalone public dataset. Its results should therefore be read as a reported comparison within a selected sample—not an official URA bedroom-level price index, or a fresh measurement of buyer appetite today.
What does the three-year sale tell us?
The Marina Bay Residences owner’s experience brings something tangible to those percentages: time. She reportedly put the apartment on the market in 2022 and completed her sale in August 2025. The eventual selling price was only slightly above what she had paid about nine years earlier.
The arithmetic is straightforward. The $50,000 increase amounts to approximately 3.2% of the original $1.55 million purchase price, across the whole holding period. That is a calculation from the reported prices, not an annual return and not her investment profit.
Her experience also illustrates why price growth and ease of selling need separate treatment. The reported sale establishes an eventual price and a lengthy marketing period; it does not establish how the asking price changed, how many offers she received, or how often viewings took place.
One owner’s wait cannot supply an average selling time for one-bedroom condos. Nor can the study’s price-growth figures fill that gap: a comparison of completed transactions answers a different question from how long owners had to wait for those transactions. The useful lesson is to keep the evidence attached to the question it actually answers.
Does rental demand make the resale easier?
The evidence supplied does not establish the first half of the familiar “easy to rent, hard to sell” description. URA provides private residential rental-contract data, and its data structure can include bedroom counts for non-landed homes. Those records help establish rents being agreed; they do not, on their own, establish how quickly a particular apartment found a tenant.
A rental contract and a completed sale also record different decisions. Conceptually, the tenant is choosing somewhere to live for the tenancy, while the buyer is accepting an ownership commitment and an eventual resale outcome. It is therefore sensible to examine the two markets separately rather than treating a signed tenancy as evidence of an easy future sale.
For a specific apartment, asking “what rent did it achieve?” is useful. Asking “how long was it empty before that tenancy?” adds another dimension. A high monthly rent and a short wait for a tenant are not the same measurement.
The same distinction applies to yield. Dividing annual rent by the purchase price produces a gross rental yield; it does not deduct ownership expenses or account for periods without rent. Without the Marina Bay Residences seller’s rental receipts and costs, her total return remains unresolved. The reported purchase and sale prices alone cannot settle it.
Why the next buyer matters
The reported resale gap makes the identity of the next buyer a useful way to think about a purchase. Rather than assuming that every affordable private apartment has the same audience, consider what the actual layout allows someone to do.
As a practical comparison, a buyer who needs a separate bedroom for a child or a dedicated room for working from home would have to compromise in a one-bedder. Someone buying alone may find that same layout entirely sufficient. These are possible household choices, not findings that explain the study’s measured performance.
Bedroom count is therefore a starting description, not a complete comparison. A useful project-level investigation would hold more things steady: location, remaining lease, building age, internal space and the total price. Otherwise, a comparison between a central one-bedder and a much larger suburban home can mix several differences together.
URA’s transaction and rental resources provide a starting point for researching actual deals rather than relying only on advertisements. But the reported ERA averages do not isolate how much of the gap came from layout, location, tenure or purchase timing. That causal breakdown remains unanswered in the evidence available here.
The sale price is only one part of the outcome
For the anonymous seller, $1.6 million was the achieved exit price—not an asking price or an agent’s estimate. Yet the $50,000 difference from her purchase price is only the beginning of an investment calculation. Her financing, transaction and holding costs, together with any rental income, would be needed to reconstruct the result. Those details are not established by the supplied account.
That leaves two separate questions for anyone studying a similar apartment: what comparable buyers have actually paid, and what ownership would cost while waiting for the next one. Neither is answered by a rental headline alone.
The strongest finding remains a specific one: studios and one-bedders in the reported ERA sample generally gained less than larger homes, although most resold profitably. The Marina Bay Residences owner adds the human consequence the averages miss—a sale can eventually happen, while taking years to arrive.